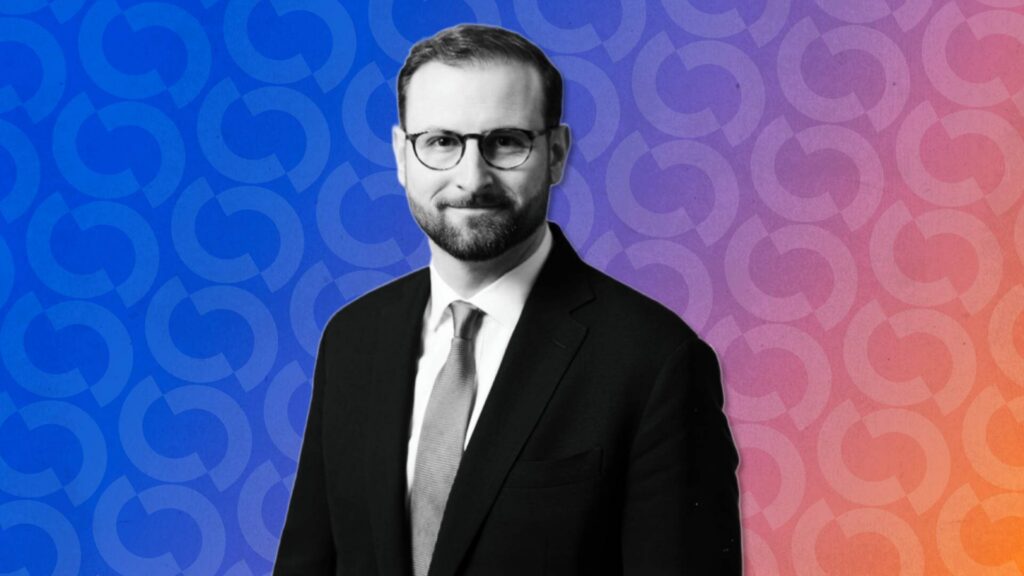
As reported on November 17, 2026, Patrick Witt, President Donald Trump’s former top crypto adviser, called the Clarity Act’s failure to clear a key US Senate procedural vote in September “a failure of American leadership.” Speaking at Solana’s Breakpoint conference in London, he said he had spent more than a year negotiating the proposed framework for crypto-market regulation.
Witt, who served as executive director of the President’s Council of Advisers for Digital Assets until October, said negotiators had resolved most policy differences but ran out of time as the midterm elections approached. In his account, political concerns about ethics overtook the bill. Democrats had raised concerns about the Trump family’s crypto ventures.
Witt acknowledged that Trump’s involvement in crypto was “arguably the issue” and said the president had agreed to two ethics provisions. Witt described one that would have barred federal officials, including the president, from issuing or sponsoring digital assets; required the president to divest certain digital assets or place them in a blind trust; and allowed state attorneys general to enforce violations. Those provisions were part of the proposed bill, not enacted rules.
Witt said a comprehensive replacement is unlikely to pass soon. Instead, he expects US crypto-market rules to be shaped more through agency rulemaking and guidance. He said parts of the Clarity Act might still be included in larger legislative packages, or lawmakers might grant narrower powers, such as authority for the Commodity Futures Trading Commission over spot crypto markets.
The Securities and Exchange Commission and CFTC have moved ahead with their own crypto rules, though House Financial Services Committee Chairman French Hill has said those efforts fall short of what the legislation would have achieved. Despite Democrats winning both chambers of Congress in the November midterms, Witt said he was “not bearish on the industry overall,” citing the continued presence of the president and regulators. Democrats were reportedly planning a broader market-structure bill of their own.